China Mineral Resources Group Co., the state-backed entity created to centralize the world's largest steel industry's iron ore purchasing, has capped a landmark year by locking in yearlong supply agreements with two of its biggest suppliers — Anglo American Plc and Rio Tinto Group — in deals that market participants now treat as events in their own right.
Bloomberg reported that the Anglo deal covers a full year of supply, while a separate agreement with Rio Tinto, first reported by Reuters, similarly binds one of the world's dominant iron ore producers to China's centralized buyer. Terms of both agreements were not publicly disclosed, but their significance lies less in tonnage than in structure: each deal further institutionalizes CMRG as the gatekeeper for a market worth more than $100 billion a year.
A Buyer That Moves the Market
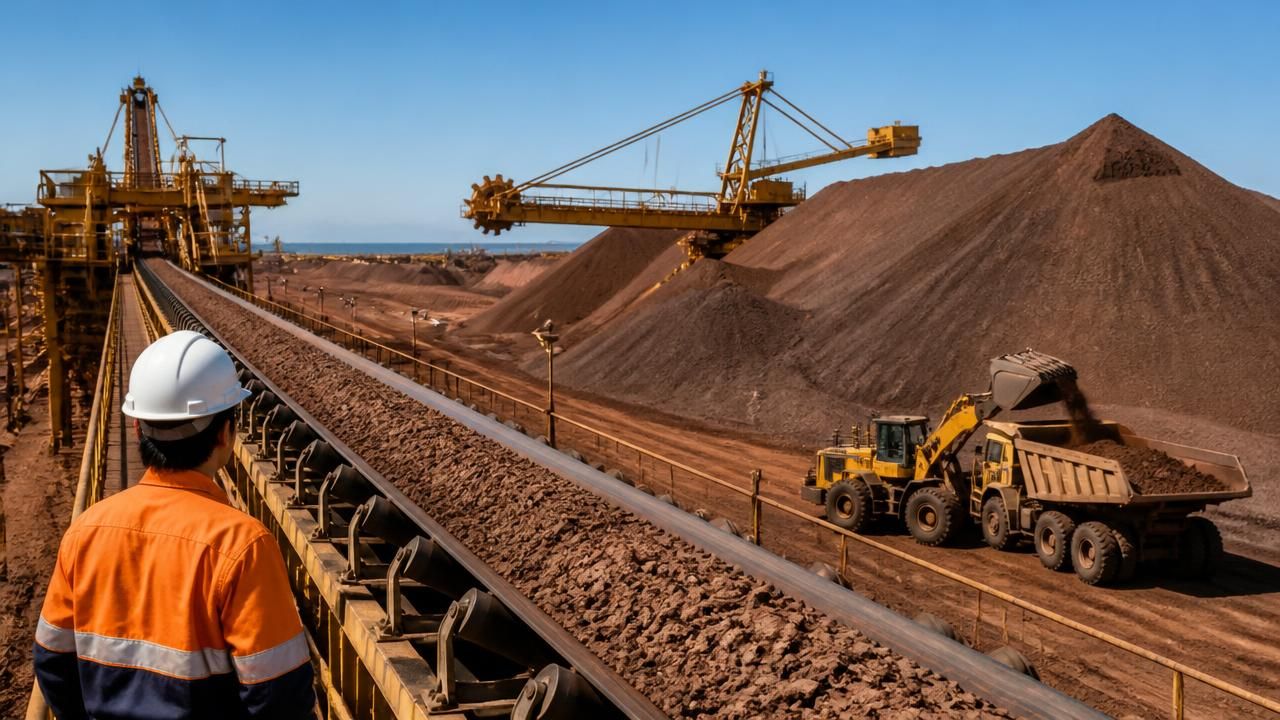
Iron ore is the backbone of steelmaking and, by extension, of China's industrial economy. The country imports more than a billion tonnes of the commodity annually, the overwhelming majority sourced from Australia and Brazil. For decades, that demand was fragmented across hundreds of steel mills, a structural weakness that Beijing believes allowed the big miners — Rio Tinto, BHP Group, Vale SA and Fortescue — to dictate terms and inflate prices.
CMRG was designed to fix that. Backed by China Baowu Steel Group, the world's largest steelmaker, and formally launched in 2022, the group consolidated purchasing mandates and negotiating authority under one roof. The strategy has been slow-burning but increasingly effective: by aggregating demand, CMRG can negotiate in bulk, push for index-linked pricing reform, and — critically — steer volumes toward suppliers willing to accept its terms.
"Each deal is a market event" — the framing offered by Bloomberg Markets, which noted that CMRG has secured agreements with two of its biggest suppliers in a year that established its dominance of the sector.
That characterization is telling. In a commodity market where trades are routine, CMRG's contracts are read as signals about pricing benchmarks, spot market direction and the balance of power between producers and the Chinese state.
Rio, Anglo and the New Bargaining Table
The Rio Tinto agreement is particularly symbolic. The Anglo-Australian miner has been one of the most exposed to Chinese policy shifts — from the diplomatic tensions that chilled trade in several commodities to the impending supply shock from the giant Simandou project in Guinea, which is expected to add significant new volumes to the seaborne market later this decade.
Anglo American, meanwhile, is in the midst of a broader corporate reshaping, having fended off a takeover approach from BHP and moved to spin off or divest several assets. A yearlong supply pact with China's state buyer offers the company something valuable: demand visibility from the single largest customer base in the industry.
The framing across outlets reflected each publication's lens. Bloomberg emphasized market structure and CMRG's growing leverage, casting the agreements as evidence that the Chinese buyer now shapes the terms of trade. Reuters, via syndication partners including MSN, led with the factual news of the Rio agreement. Specialist and aggregator sites — including nai500.com and Seeking Alpha — framed the Anglo deal in investor terms, focusing on what a locked-in Chinese buyer means for the miner's revenue outlook and share price. None of the reports disclosed contract volumes or pricing formulas, a reflection of how opaque these negotiations remain.
Why It Matters
- Pricing power: A unified Chinese buyer weakens the traditional producer advantage in benchmark negotiations and could push the industry further toward Chinese price indices, a long-standing Beijing objective.
- Supply security: Long-term agreements insulate Chinese mills from spot market volatility and from disruptions tied to geopolitical flare-ups with Australia.
- Producer dependence: Miners gain volume certainty but cede negotiating flexibility — a trade-off shareholders will be watching closely.
- Market signaling: Because CMRG deals are rare and closely watched, each announcement moves sentiment and, potentially, prices.
The broader context is one of diversification. China has aggressively pursued alternative supply — expanding Brazilian imports, investing in African projects including Simandou, and boosting domestic ore production — all aimed at reducing reliance on Australian supply without triggering a price war.
The Road Ahead
For CMRG, the challenge is sustaining momentum. Centralized buying works best when mills comply, and reports over the past two years have suggested uneven participation from private steelmakers wary of surrendering procurement autonomy. There is also the question of whether miners will accept structural changes to pricing, or simply sign deals while preserving their preferred index-linked formulas.
What is clear is that the era of the fragmented Chinese buyer is ending. Two yearlong agreements with major suppliers in a single year would have been unthinkable a decade ago. Now they are treated as routine — or rather, as market events. For a $100 billion industry, that shift in gravity, from the Pilbara to Beijing, may prove to be the defining story of the decade.