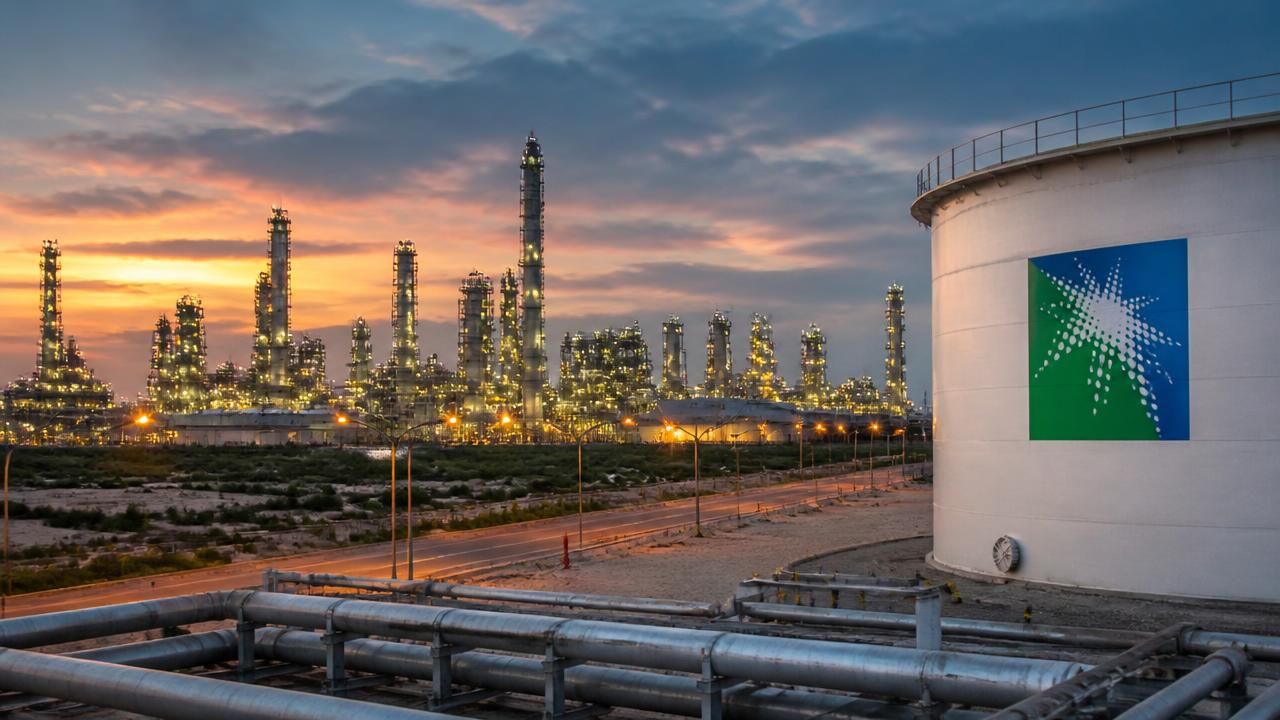
Saudi Aramco reported higher third-quarter earnings on Tuesday, with profit lifted by a sharp jump in refining income and by crude prices pushed upward amid the conflict between Iran and its adversaries. But the headline number depended heavily on which wire service you read: Bloomberg reported a 9% increase in profit, while Reuters put the rise at 34.5%. Both figures were attributed to the same three-month period, leaving analysts and investors to reconcile two very different descriptions of the same quarter.
The divergence underscores how closely the market is watching the kingdom's state oil giant, whose results function as a barometer for global energy prices, Gulf fiscal health and the wider trajectory of the war.
A quarter shaped by war
According to Bloomberg, whose report was carried by markets correspondent Mitchell Ferman, Aramco's profit climbed 9% in the third quarter, helped by a jump in earnings from its refineries and by the Iran war driving oil prices higher. The company's realized oil selling price was roughly 35% higher in the quarter than a year earlier — a striking uplift that reflects both the physical tightness of the market and the geopolitical risk premium embedded in crude benchmarks.
Reuters, reporting on the same release, characterized the quarter far more dramatically, describing a 34.5% rise in third-quarter profit. Neither wire immediately published a reconciliation of the two figures, and the discrepancy may reflect different baselines — net income versus a broader profit measure, or year-on-year versus sequential comparisons — or adjustments for one-off items. Requests for clarification to Aramco were not immediately answered.
"The company's oil selling price was about 35% higher in the quarter from a year earlier" — Bloomberg, citing Aramco's quarterly results
Refining, not just crude
What both accounts agree on is the composition of the beat. Aramco has spent years pushing downstream — buying and integrating refining and petrochemical capacity through its trading arm and its stake in ventures such as the SATORP and Luberef complexes — precisely to blunt the cyclicality of raw crude sales. That strategy paid off this quarter, as refining margins widened alongside product cracks.
The downstream boost matters because it insulates the company from the price-cap and demand-destruction risks that hang over upstream volumes. When crude rallies on supply fear, refiners with feedstock access can capture additional spread; when crude falls, the downstream cushion softens the blow. For a company that pays out one of the world's largest dividends — a cornerstone of the Saudi government's budget — that stability is worth as much as the headline profit number.
The wider industry windfall
Aramco is not alone. The Guardian reported that nine oil companies could collectively earn more than $95 billion in profit, a figure that captures how the war-driven price spike is redistributing cash flows across the integrated majors and national oil companies alike. For consumers, that translates into elevated pump prices and renewed inflationary pressure; for producer governments, it means a fiscal reprieve at a moment when defense spending is rising.
That dual dynamic — windfall profits alongside higher security costs — is the defining tension of the current oil cycle, and it is playing out most visibly in Riyadh.
Security, markets and the defense pact
The earnings arrived against a backdrop of escalating risk. CNBC reported that oil prices rose after the International Energy Agency warned about market constraints, and after Saudi officials said Aramco facilities had been attacked. Those strikes echo the 2019 Abqaiq and Khurais drone and missile assaults, which briefly knocked out roughly half of Saudi production and produced the largest single-day jump in Brent crude history. Markets have since learned to price such events more quickly, though the buffer of spare capacity and strategic inventories remains thinner than in previous cycles.
Meanwhile, MarineLink reported that Gulf stock markets rose in the wake of a Saudi defense pact, suggesting investors read the new security arrangement as a stabilizing counterweight to the attacks. Regional bourses have been volatile since the conflict widened, with banking and petrochemical names particularly sensitive to both oil prices and the perceived risk of infrastructure damage.
Framing the story
The coverage reveals three distinct lenses on the same event. Bloomberg framed the quarter through the mechanics of price and margin — a company story about operational leverage. Reuters emphasized the magnitude of the earnings beat, a framing that speaks to investor expectations and shareholder returns. The Guardian, by contrast, treated Aramco as one data point in a broader story about industry-wide profiteering during a war, shifting the emphasis from corporate performance to distributional fairness.
All three readings are legitimate, and together they explain why Aramco's results resonate far beyond Riyadh. The company produces roughly one in every eight barrels of oil consumed globally; its pricing decisions, dividend policy and capital spending shape everything from Asian refinery economics to the viability of energy-transition spending elsewhere.
What to watch
- Reconciliation of the profit figures: whether the 9% and 34.5% measures reflect different baselines or revised reporting.
- Dividend sustainability: Aramco's payout remains central to Saudi fiscal planning, particularly as defense outlays climb.
- Facility security: further attacks on Abqaiq, Ras Tanura or Red Sea export infrastructure would test the market's spare-capacity buffer.
- IEA guidance: continued warnings on market constraints could keep a risk premium baked into crude into 2027.
- The defense pact's economic spillover: whether Gulf risk premiums compress enough to support regional equity and sovereign debt markets.
For now, the quarter confirms a simple arithmetic: war in the Gulf raises the price of Saudi barrels, fattens refining margins and fills the kingdom's treasury — even as it raises the cost of defending the infrastructure that produces them.