Berkshire Hathaway shares have clawed their way back to record territory, closing at an all-time high and fully erasing the steep losses suffered in the aftermath of Warren Buffett's surprise announcement at the 2025 annual shareholders meeting that he would step down as chief executive, according to CNBC. The recovery caps a volatile 18-month stretch in which investors were forced for the first time in six decades to price Berkshire without Buffett at the helm.
How the story unfolded
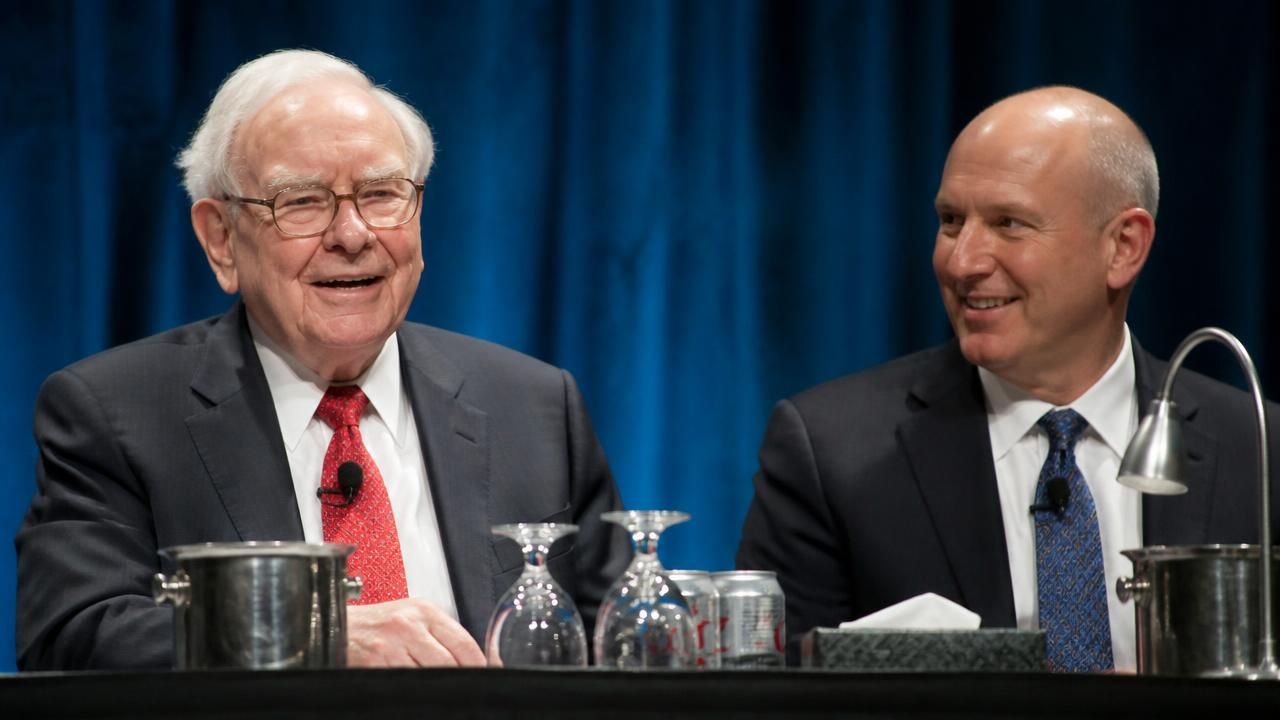
The sequence is now familiar to Berkshire watchers. At the May 2025 gathering in Omaha — long billed as "Woodstock for Capitalists" — Buffett stunned the arena by disclosing that Greg Abel, the longtime head of Berkshire's non-insurance operations, would take over as CEO at year-end, with Buffett remaining chairman. Shares fell sharply in the days that followed, as investors grappled with the departure of the company's defining figure.
That slump persisted far longer than many expected. CNBC notes it took almost 18 months for the stock to recover "all the ground" lost after the announcement — an unusually extended stretch for a conglomerate whose shares have historically been treated as a defensive bellwether. Along the way, coverage of the company turned noticeably more ambivalent: one CNBC piece published this week carried the headline "Buffett remains active at 96, but Berkshire's shares aren't doing much," a framing that emphasized stagnation rather than recovery.
Framing the rally: four outlets, four stories
The same price move has generated markedly different narratives depending on where you read it.
- CNBC framed the milestone as the resolution of "the Buffett blues" — a psychological catharsis as much as a financial one, with the stock finally shaking off the succession overhang.
- MSN emphasized relative strength: Berkshire "bucked" a broader market sell-off, rallying to its highest level since Buffett announced his departure — positioning the stock as a haven at a moment when the rest of the market was falling.
- Seeking Alpha read the move as a market referendum, describing the new high as "a vote of confidence" in Abel — an explicit endorsement of the incoming chief executive rather than a nostalgic nod to his predecessor.
- A second CNBC item struck a more skeptical note, suggesting that even as Buffett remains energetically involved at 96, the shares had been listless until very recently.
Together, the coverage captures a genuine debate: is the record high a verdict on Abel's stewardship, a flight to safety during a turbulent market, or simply a delayed normalization after an emotional sell-off?
The Abel referendum
For shareholders, the most consequential reading is the one offered by Seeking Alpha. Berkshire's succession was engineered with unusual care — Abel was publicly designated as Buffett's successor years before the formal handover, and the company's operating subsidiaries, insurance reserves and enormous cash pile were structured to run without the founder's daily involvement.
If the market is now willing to pay a record price for Berkshire with Abel in the CEO chair, the succession discount that dogged the stock through 2025 appears to have closed.
That matters well beyond Omaha. Berkshire is one of the largest companies in the world by market value, a major holder of equities including Apple and Bank of America, and the parent of GEICO, BNSF Railway and an array of industrial and energy businesses. Its valuation is a proxy for investor confidence in the post-founder conglomerate model more broadly.
Why now?
The rally's timing — coinciding with a broader market sell-off — is instructive. Berkshire's towering cash position and insurance-heavy earnings mix have historically made it a destination for capital fleeing volatility. If MSN's framing is correct, the same dynamic that lifted Berkshire in past downturns is operating again, just under new management.
The countervailing view is less flattering. A stock that took 18 months to recover a single announcement-driven drawdown is not obviously a momentum story, and skeptics have long argued Berkshire trades at a persistent conglomerate discount: the sum of its parts is worth more than the whole. Recent buybacks, meanwhile, have slowed as Buffett and Abel have signaled that valuations across the market look rich — a stance that can cap upside even as it protects downside.
What to watch
Attention now shifts to several catalysts. Abel's first full shareholder letter and annual meeting as CEO will be scrutinized for signals on capital deployment, particularly whether Berkshire finally puts its record cash pile to work. Investors will also watch how aggressively the company repurchases stock at current prices, and whether the insurance underwriting cycle continues to cooperate.
Buffett's continued activity at 96 — he remains chairman and, by all accounts, a daily presence — cuts both ways. It offers continuity and reassurance to long-time holders, but it also keeps the founder's eventual full departure, and the question of what Berkshire looks like without him entirely, on the horizon.
For now, the market has rendered its verdict: the handover, once a source of anxiety, has become a non-event. The Buffett premium has faded — and the Abel discount, if it ever existed, appears to have gone with it.