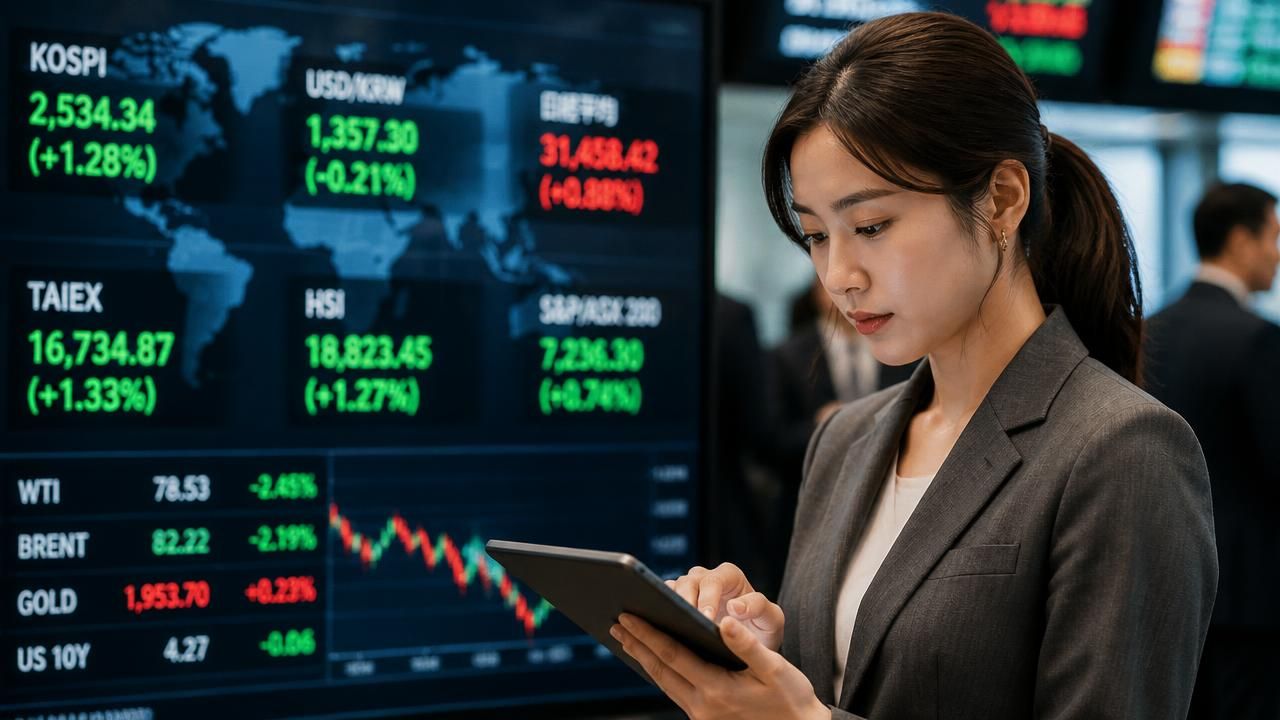
Asian equities advanced in the latest session, tracking a firmer Wall Street close and drawing support from a pullback in crude oil, as softer US labour-market data eased pressure on the Federal Reserve to keep raising interest rates. Government bonds steadied, and the euro extended its decline against the dollar.
The session capped a week of sharp swings in which sentiment flipped repeatedly — a volatility that is itself the story. Headlines across financial outlets told two apparently contradictory tales about the same market, a sign of how delicately balanced investors' expectations have become.
“Asian stocks drop as oil spike fans rate hike bets, eyes on US jobs” — versus — “Asian shares mostly rise, cheered by a US rally and easing oil prices”
Both framings were accurate, just separated by a few trading sessions and one key variable: the direction of oil.
Oil Is Driving the Rates Narrative
The immediate trigger for the earlier selloff was a spike in crude prices, which traders read as an inflationary shock that would force central banks to keep policy tight for longer. When oil retreated, the calculus reversed almost mechanically: cheaper energy means less pressure on headline inflation, which in turn means less pressure on the Fed to tighten. Equities rallied on that logic, and bonds — which had been routed by the prospect of higher-for-longer rates — found their footing.
The link between crude and rate expectations has become unusually tight this cycle. Energy is one of the few components of inflation that central banks cannot influence directly, so a sustained oil spike tends to harden the market's view that policymakers will have to compensate elsewhere. A retreat does the opposite, and quickly.
Bonds Steady Ahead of the PCE Test
Treasuries steadied as investors positioned ahead of the release of the Personal Consumption Expenditures price index, the inflation gauge the Federal Reserve itself prefers. The wait mattered: the PCE print is one of the last major data points policymakers will see before their next rate decision, and it carries more weight than the headline consumer price index in shaping the Fed's internal debate.
The softness in US jobs data released earlier gave the market room to trim its expectations for further tightening. A cooling labour market is precisely what the Fed has been trying to engineer — it argues that demand is slowing and that the risk of entrenched inflation is receding. But it cuts both ways for equities, since a weakening jobs picture can signal an approaching downturn just as easily as it signals a policy pivot.
Europe Follows Asia's Lead
European shares rebounded from a bond-market rout on the same easing Fed rate-hike bets, with the recovery in equities tracing directly back to the shift in rate expectations that began in Asia. The bond rout that preceded it had been severe enough to unsettle credit markets and force a reassessment of valuations across asset classes, so the stabilisation was welcomed well beyond fixed income.
The sequence — Asia leads, Europe follows, US futures set the tone — has become a familiar pattern in a market where rate expectations, rather than earnings, are doing most of the driving.
The Euro's Slide
The euro extended its drop against the dollar, a move consistent with the broader rate story. When markets price in a more dovish Fed, the dollar should typically weaken; the euro's decline instead reflects the relative weakness of the eurozone's own growth outlook and the European Central Bank's more cautious posture. Currency markets, in other words, are trading the divergence between two central banks rather than a single Fed signal.
What to Watch
- The PCE print: A hotter-than-expected reading would revive rate-hike bets and likely reverse the week's gains in both stocks and bonds.
- Oil's next move: Further declines would reinforce the disinflation narrative; a renewed spike would put the selloff back in play.
- US labour data: Continued softening supports the pause-and-hold case, but too much weakness would shift attention from inflation to recession.
- The dollar and the euro: The gap between Fed and ECB expectations remains the dominant force in currency markets.
The Bigger Picture
The competing headlines obscure a simpler reality: markets are no longer trading fundamentals so much as probabilities. Each data release nudges the odds of another rate increase, and every asset — Asian equities, Treasuries, European stocks, the euro — is being repriced off that single number.
That makes the current rally fragile. It is built on easing rate expectations and falling oil, not on improving corporate earnings or a durable reacceleration in growth. Should the PCE data surprise to the upside, or should crude prices turn higher again, the same mechanism that lifted stocks this week would work in reverse — quickly, and across every market that took part in the rebound.
For now, investors are content to read softer jobs data and cheaper oil as unambiguously good news. The coming days will determine whether that interpretation survives contact with the inflation data.