For the better part of a year, one word has haunted enterprise software boardrooms: “SaaSpocalypse.” The thesis was simple and brutal — if large language models can read, write, and reason across a company’s scattered tools, then the sprawling stack of subscription software that corporate life runs on could be reduced to a prompt. Why pay per seat for project trackers, databases, and documentation platforms when an AI agent can assemble them on demand?
Atlassian, the Australian-American company behind Jira, Confluence, and Trello, sat squarely in the crosshairs. Its products are the connective tissue of modern engineering and knowledge work; its business model is the archetype of the per-seat SaaS economics the apocalypse narrative says is doomed. Yet as the year closed, the story inverted. Atlassian didn’t collapse — it rallied, and the “SaaSpocalypse” debate shifted from an obituary to an open question.
What the ‘SaaSpocalypse’ actually predicted
The term emerged among investors and analysts as shorthand for a feared cascade: AI agents that could traverse and synthesize a company’s entire software estate, making migrations to platforms like Atlassian’s less attractive — or unnecessary. In its most extreme form, the argument suggested AI would simply build bespoke replacements for every SaaS category, vaporizing an entire industry of recurring-revenue businesses.
That fear drove sharp volatility across software stocks, with the debate intensifying as valuations swung wildly from session to session. The question, as one CNBC framing put it, was whether the “SaaSpocalypse” was finally fading — or merely pausing.
Atlassian’s answer: a rally, not a rout
Atlassian’s year-end results and subsequent share performance delivered the most concrete rebuttal. Coverage across the business press converged on the same headline: the “SaaSpocalypse” was meant to kill Atlassian — and it soared instead. The company reported a strong close to the year, and its stock shook off the AI-fear discount that had weighed on the sector.
Notably, Atlassian was not alone in the overnight bounce. Other enterprise software names also moved higher after earnings, prompting the question of whether the whole category was being re-rated as investors concluded that the disruption thesis had been oversold.
Cannon-Brookes: design, humans, and why AI adds usage
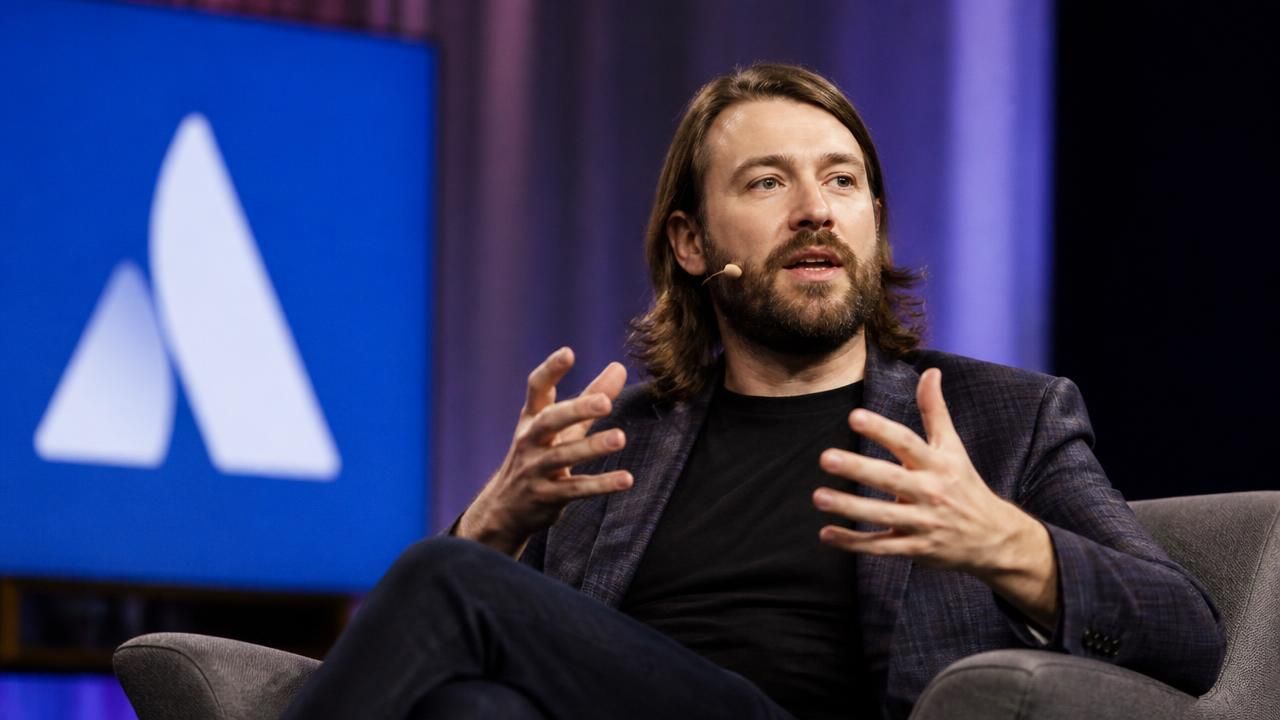
The clearest counterargument has come from Atlassian co-founder and CEO Mike Cannon-Brookes, who used a lengthy appearance on Decoder, The Verge’s interview show, to dismantle the premise. His core argument, in essence:
AI tools can read your systems, but reading is not the same as running a business. The value is in human-designed workflows, shared context, and the coordination layer that turns information into decisions — and that is precisely what Atlassian sells.
Cannon-Brookes also pointed to a structural argument that cuts against the doom thesis: all of Atlassian’s products are different expressions of a single underlying platform. That architecture, he argued, shapes both how the company builds and how quickly it can absorb AI capabilities into the tools customers already use.
Crucially, he rejected the zero-sum framing. Rather than AI cannibalizing Atlassian’s usage, he described AI as increasing it — agents and copilots generating more activity inside the platform, not less. The counterintuitive outcome, in his telling, is that the arrival of generative AI has made the question of “where does the work live” more important, not less.
‘Context as king’ — and the tokenomics problem
Diginomica framed Atlassian’s strong year-end around a different but complementary idea: with the SaaSpocalypse and a parallel “tokenomics” crisis both failing to derail the company, context is king. Models are abundant; proprietary, well-structured organizational context is scarce. The systems that hold that context — who is working on what, why a decision was made, how a project connects to a strategy — become more valuable, not less, when AI can act on them.
The tokenomics angle is the cost side of the same coin. As enterprises scale AI workloads, inference costs and token consumption become real budget lines, forcing buyers to ask which AI spending produces durable value. Platforms that already anchor a company’s operational data have an advantage in that calculation.
How the framing shifted
Across outlets, the same facts produced different stories:
- The Verge treated the episode as a test of a thesis — the “SaaSpocalypse that wasn’t” — and gave Cannon-Brookes room to argue that design and human users remain the moat.
- Financial outlets such as CNBC and MSN zeroed in on the market mechanics: wild swings in software stocks, earnings-driven rallies, and whether the apocalypse trade is finally unwinding.
- The Next Web leaned into the irony, casting Atlassian as the company the narrative was supposed to kill.
- Diginomica pushed past the binary, arguing that context — not code generation — is the scarce asset.
What comes next
The honest answer is that the debate is unresolved. Software stocks remain volatile, and the underlying question — whether AI compresses or expands the SaaS market — will be settled by usage data, renewal rates, and pricing power over the next several quarters, not by argument.
But the Atlassian episode offers an early data point that cuts against the most fatalistic version of the thesis. If AI were truly commoditizing the category, the platforms holding the deepest organizational context should be the first to crack. Instead, one of them just posted a strong year and watched its stock rally while the pundits argued about its death. For now, the SaaSpocalypse remains a forecast — and forecasts, as Cannon-Brookes would be the first to note, are not the same as context.