The Securities and Exchange Commission is preparing a plan to widen investor access to private markets, according to a report by Livemint, a move that would mark one of the most consequential shifts in U.S. securities regulation in decades. The proposal could allow more retail investors to participate in private funds, private companies, and other alternative assets that have historically been reserved for wealthy individuals and institutions.
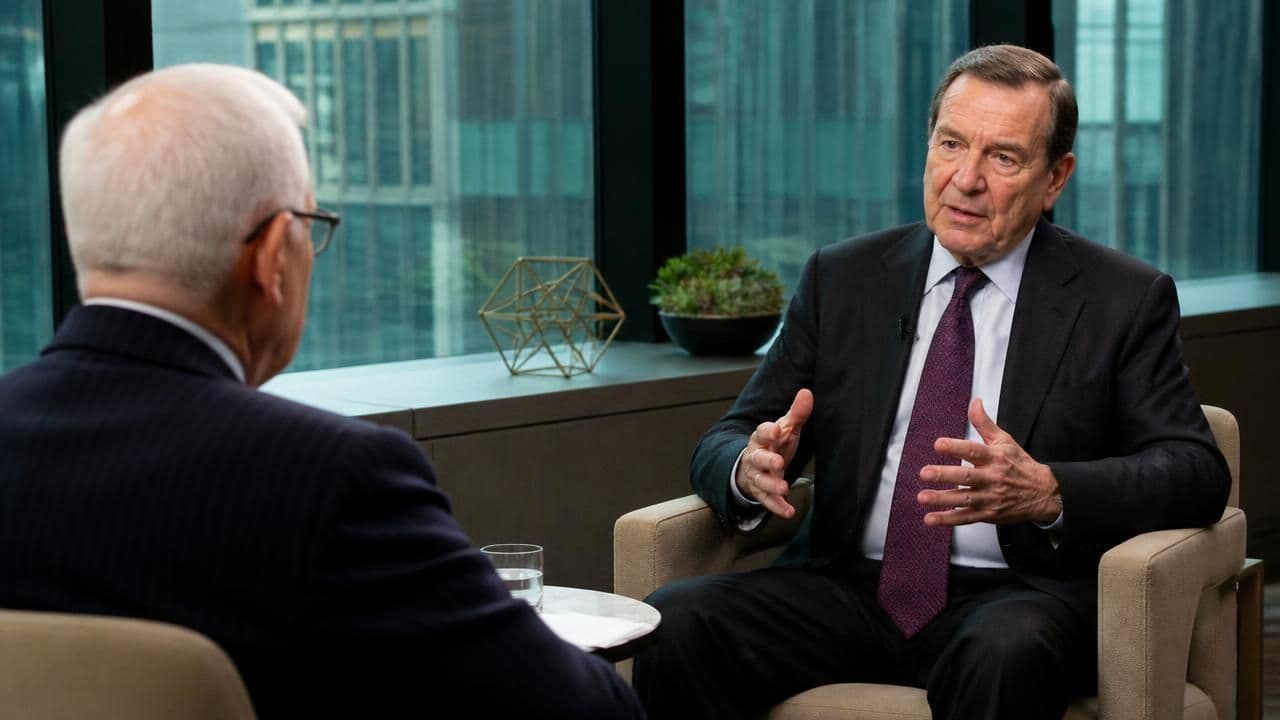
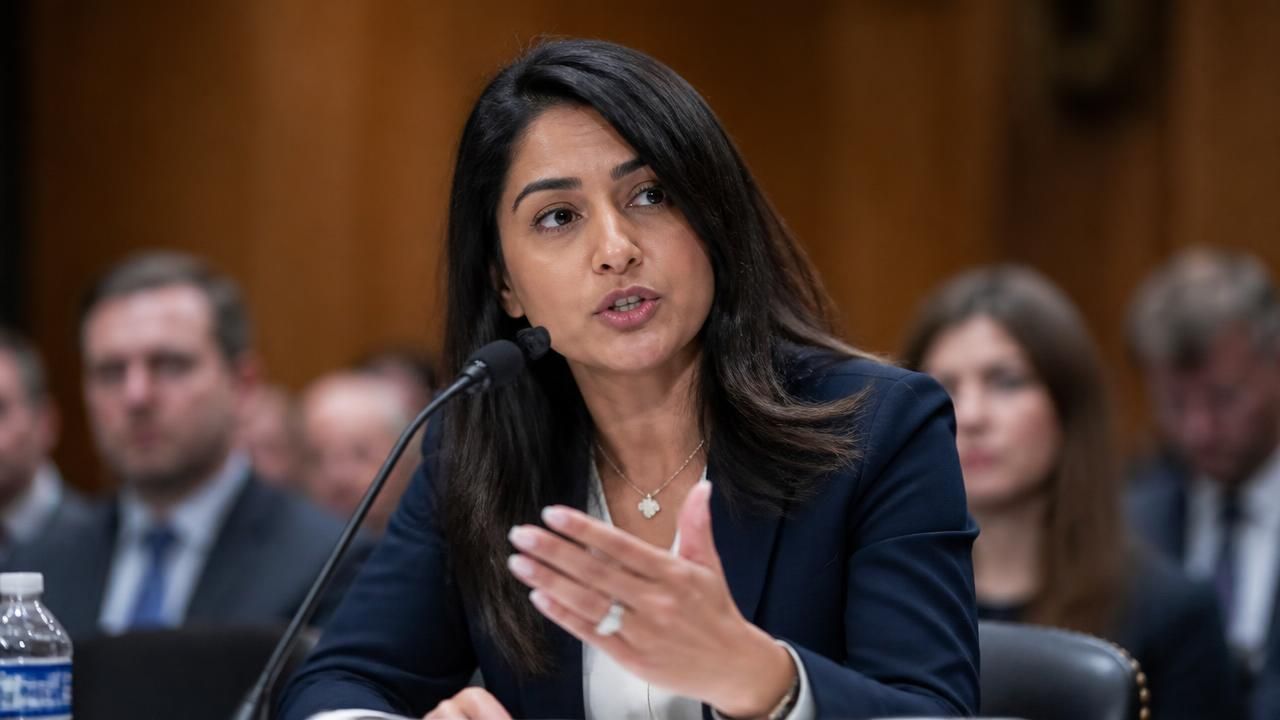
The debate moved into public view this week at Georgetown University’s Financial Markets Quality Conference, where Alpa Patel, a partner at Kirkland & Ellis and a former SEC regulator, sat down with Bloomberg’s Romaine Bostick to discuss the state of private markets and the regulatory framework around opening access to the public. The Bloomberg Markets interview was syndicated across platforms, including Yahoo Finance, where a temporary rate-limit error underscored the high demand for clarity on the rules.
Patel’s perspective carries weight because she has seen the issue from both sides: inside the SEC, where rules are written and enforced, and in private practice, where capital markets clients navigate those rules. Her remarks at Georgetown did not announce a specific rulemaking, but they underscored that the SEC is actively weighing how to modernize its framework for a market that has grown far beyond its original boundaries.
Why Private Markets Matter
Private markets have exploded over the past two decades. Private equity, private credit, venture capital, and real estate funds now manage trillions of dollars. The number of U.S. public companies has fallen by roughly half since the peak in the late 1990s, while private capital has filled the gap. That shift has left ordinary investors increasingly shut out of the fastest-growing segments of the economy.
The SEC’s accredited investor definition, which generally requires income of $200,000 or net worth of $1 million excluding a primary residence, determines who can access many private offerings. The agency has faced pressure to update that threshold, which has not been adjusted for inflation in decades. A broader access plan could expand the definition, create new vehicles for retail participation, or ease restrictions on private funds.
Retail Is Already In, American Banker Argues
But as the SEC prepares its plan, American Banker reports that retail investors are already in private markets. The headline: “SEC pushes private market access, but retail is already in.” The publication points to a growing array of listed and non-listed vehicles that give individuals exposure to private assets: interval funds, business development companies (BDCs), non-traded REITs, tender-offer funds, and increasingly, tokenized or secondary platforms.
These structures have existed for years, but they have gained scale recently. BDCs, which are regulated under the Investment Company Act of 1940, allow retail investors to buy shares in a portfolio of private loans and middle-market companies. Interval funds, which permit limited periodic redemptions, have become a favorite wrapper for private credit and real estate. Non-traded REITs, after a regulatory cleanup, have raised billions from retail investors.
American Banker’s framing suggests the SEC’s push is less about opening a closed door and more about catching up with a market that has already found workarounds. The risk is that retail investors may be accessing private markets through vehicles that are less transparent, less liquid, and more expensive than traditional mutual funds or ETFs.
The Regulatory Balancing Act
The SEC’s challenge is to expand access without repeating the mistakes of the past. Private markets are illiquid; valuations are often stale; fees are higher; and disclosure is lighter than in public markets. Regulators worry about retail investors being sold complex products they do not understand. Industry advocates argue that sophisticated retail investors should be allowed to diversify into alternatives that institutions have long used to boost returns.
At Georgetown, Patel’s discussion with Bloomberg’s Bostick focused on that framework. The Financial Markets Quality Conference, hosted by Georgetown’s Psaros Center for Financial Markets and Policy, brings together regulators, academics, and industry practitioners to debate market structure. The setting was apt: the SEC’s plan will require input from all of those constituencies.
“SEC pushes private market access, but retail is already in,” American Banker reported, capturing the central paradox of the debate.
What Comes Next
The SEC has not released a formal proposal, and any rule would go through a notice-and-comment period. That process could take months or longer, especially with a divided commission and intense lobbying from both investor-protection groups and the asset management industry. The agency could also pursue narrower changes, such as updating the accredited investor definition or modernizing the rules for interval funds and BDCs.
For now, the direction is clear: the SEC wants to widen the door to private markets. The question is whether the door should be opened wider, or whether retail investors are already walking through it—and whether the existing vehicles are safe enough. As the Georgetown discussion made clear, the regulatory framework is not static. It is being rewritten in real time, under pressure from markets that have already moved ahead of the rules.
- Key point: SEC is preparing a plan to widen investor access to private markets, per Livemint.
- Industry view: Alpa Patel, former SEC regulator and Kirkland & Ellis partner, discussed the regulatory framework at Georgetown with Bloomberg’s Romaine Bostick.
- Counterpoint: American Banker reports retail investors already access private markets via interval funds, BDCs, and non-traded REITs.
- Next step: Any SEC proposal would require public comment and could face legal and political challenges.