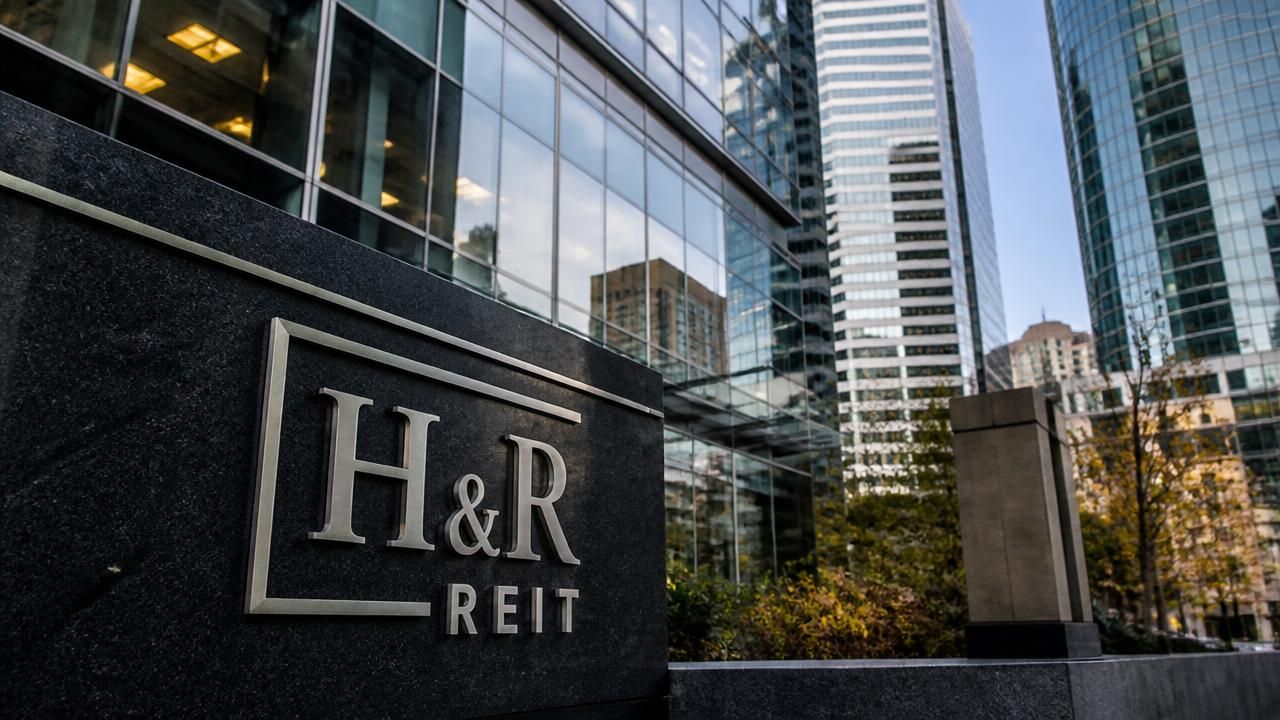
A C$6.7 billion (US$4.7 billion) plan to dismantle one of Canada's largest real estate investment trusts is running into an increasingly public wall of opposition, as some of the world's biggest pension funds line up against a transaction that would transfer a substantial slice of H&R Real Estate Investment Trust's property portfolio to the family of its chief executive officer.
According to Bloomberg Markets, the shareholder revolt is widening, turning what was pitched as a value-unlocking restructuring into a governance fight with global institutional money on one side and the company's controlling family on the other.
What the deal actually does
H&R, a Toronto-based landlord whose holdings have historically spanned office towers, retail plazas, industrial parks and residential developments across Canada and the United States, has proposed a breakup that would divide the trust's assets among different owners rather than keep them inside a single publicly traded vehicle.
The most contentious element is the destination of a portion of that portfolio: entities connected to the family of H&R's chief executive. In effect, a public company's assets would migrate, at least in part, into private hands — a structure that turns an ordinary real estate transaction into a related-party deal requiring an unusually high level of scrutiny.
Who is fighting — and why
Bloomberg reports that some of the largest pension funds in the world are aligning against the transaction. That is significant because pension funds are precisely the patient, long-horizon holders that real estate trusts cultivate: index funds and retail investors come and go, but a large pension allocator taking a public stand against management is a rare and pointed rebuke.
The objections appear to cluster around a handful of questions that typically decide the fate of related-party restructurings:
- Valuation. Are the properties being transferred priced at, below, or above fair market value — and who determined that number?
- Process. Was the deal negotiated at arm's length, and did independent directors have real authority to say no?
- Alternatives. Could unitholders have received more through a straightforward sale, a liquidation, or a competitive auction?
- Alignment. Does management benefit in ways that ordinary unitholders do not?
"Some of the world's biggest pension funds are lining up against a deal that would hand a chunk of the Canadian landlord's properties to the family of its chief executive officer." — Bloomberg Markets
The governance question at the center
H&R has long been associated with its founding Hofstedter family, and that history is both the source of the trust's identity and the root of the current dispute. When a company's CEO is also part of the family acquiring assets, the transaction is not merely a financial decision — it is a test of whether minority unitholders have meaningful leverage over insiders.
Canadian securities rules generally require related-party transactions to be approved by a majority of disinterested unitholders, often alongside a formal valuation and the involvement of an independent special committee. The fight now unfolding is, in practical terms, a campaign to influence that vote: pension funds talking to proxy advisers, filing concerns publicly, and signaling that they may oppose the arrangement regardless of what the board recommends.
Why now: the REIT discount era
The clash fits a broader pattern across North American real estate. Publicly traded REITs have traded at persistent discounts to the underlying value of their properties, in part because of higher interest rates, refinancing costs and weak office demand. That discount has created a powerful incentive for insiders: if the market values the portfolio at, say, 70 cents on the dollar, buying assets out of the public vehicle can look attractive to management and expensive to everyone else.
That dynamic has produced a wave of take-private proposals, spin-offs and simplification transactions over the past two years. Each one is judged less on its strategic logic than on its fairness — and the H&R case is shaping up as a test of how much scrutiny Canadian markets apply when the buyer and the seller share a surname.
What happens next
The outcome will depend on the arithmetic of the unitholder vote and on whether the company can win over a critical mass of institutional holders. If pension funds hold their ground, H&R's board faces two uncomfortable options: sweeten the terms for minority owners, or push ahead and risk defeat — and the reputational damage that comes with losing a vote on a deal involving the CEO's family.
For the broader market, the signal matters beyond one landlord. A successful revolt would embolden institutional investors to challenge insider-friendly restructurings elsewhere; a successful deal would demonstrate how durable the REIT discount arbitrage remains, even against the combined weight of global pension money.
About this report
This article draws on reporting from Bloomberg Markets on the H&R REIT transaction. Three additional items reviewed for this piece, syndicated from Wikinews, were returned as inaccessible placeholder pages containing only technical access notices rather than reporting, and contributed no verifiable information to this story.