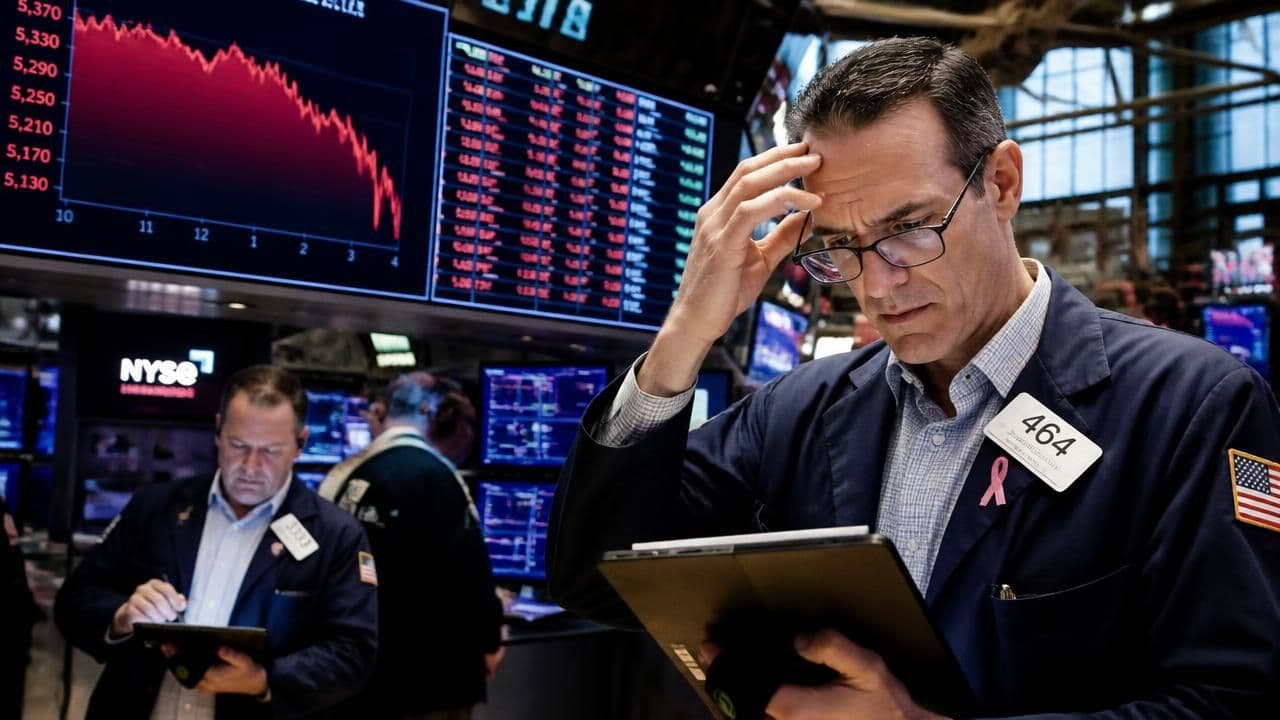
Asian equity markets opened sharply lower on Wednesday, extending a selloff that began in New York, as a deepening rout in semiconductor and artificial-intelligence stocks rippled across the region. The decline, described by Bloomberg Markets as a broad regional slump "from the open," marks the latest leg of a volatile stretch for the global AI trade, which has powered equity gains for much of the past two years but is now wobbling under the combined weight of disappointing corporate earnings and rising political risk in Washington.
A Selloff That Follows Wall Street Home
The proximate trigger was a punishing session for chipmakers in the United States, where the AI-linked names that have dominated index returns came under sustained selling pressure. According to Bloomberg's markets wrap, the rout intensified "amid growing concern that Democrats will seek tighter regulation of the artificial intelligence industry" following the election — a political overhang that investors had largely discounted until this week.
"Asian stocks slumped from the open after a post-election rout in chipmakers deepened on Wall Street amid growing concern that Democrats will seek tighter regulation of the artificial intelligence industry."
Because Asia's technology supply chain — foundries, memory makers, chip-equipment vendors and the contract manufacturers that assemble AI servers — is tightly bound to U.S. demand and sentiment, moves in American semiconductors transmit quickly into Seoul, Taipei, Tokyo and Shanghai. Syndicated coverage carried by MSN framed the session in the same terms, presenting the Asian decline as a direct continuation of the U.S. selloff rather than a regionally driven event.
The AI Trade Hits a Wall
The deeper story is the unwinding of a very crowded trade. AI-linked equities have absorbed enormous capital flows on expectations of multi-year spending on data centers, accelerators and power infrastructure. That concentration has left the sector vulnerable to any signal that growth is decelerating — and this week's U.S. earnings delivered exactly that.
Yahoo Finance's coverage emphasized the earnings angle, headlining the session as a technology slump driven by "disappointing U.S. earnings." The distinction matters: where one framing locates the cause in politics, the other locates it in fundamentals. In practice, the two are reinforcing each other. Softer guidance from major AI beneficiaries has undermined the earnings case, while regulatory noise out of Washington has compressed the valuation multiple investors are willing to pay for that uncertain growth.
- Politics: Fears of tighter AI oversight from Democrats after the election have added a regulatory risk premium to the sector.
- Earnings: Weak U.S. results and cautious forward guidance from AI-exposed companies have shaken conviction in the growth story.
- Concentration: Heavy positioning in a handful of chip names amplifies moves in both directions.
Not Every Market Is Falling
Crucially, the regional picture is not uniform — a nuance lost in the headline framing of a single continental "slump." Yahoo Finance's separate market report described Asian stocks as mixed, with South Korea's KOSPI rebounding even as a selloff in Indonesia deepened.
Seoul's recovery is notable given the country's heavy weighting toward memory chips and its exposure to the AI supply chain; a rebound there suggests investors are still willing to buy selected semiconductor exposure on weakness rather than abandon the theme outright. Jakarta's weakness appears to stem from a different source entirely: concerns tied to MSCI index risk, which raises the prospect of reclassification and the passive outflows that would follow. That is a structural, country-specific issue rather than an AI story, and it highlights how a single global risk-off impulse can mask very different local drivers.
Two Stories, One Session
The divergence in coverage is itself instructive. Wire-style wraps emphasized the region-wide character of the decline, while market-focused outlets split the tape into its component parts: a tech-driven drawdown in North Asia, a rebound in Korea, and an index-driven rout in Southeast Asia's largest market. For investors, the practical takeaway is that correlation is not causation — a red screen across Asia does not mean the same thing is happening everywhere.
What to Watch
Attention now turns to three catalysts. First, the next round of U.S. semiconductor earnings and guidance, which will determine whether this is a valuation reset or the start of an earnings downgrade cycle. Second, any concrete legislative or regulatory signals from Washington on AI oversight — markets tend to price policy risk long before rules are written. Third, MSCI's review calendar and its implications for Indonesian flows, a reminder that index mechanics can move billions of dollars independently of the macro cycle.
For now, the AI trade is being tested rather than abandoned. But the combination of political uncertainty and softer earnings has reminded investors of a lesson the sector had allowed them to forget: what rallied on a single narrative can fall on a single headline.