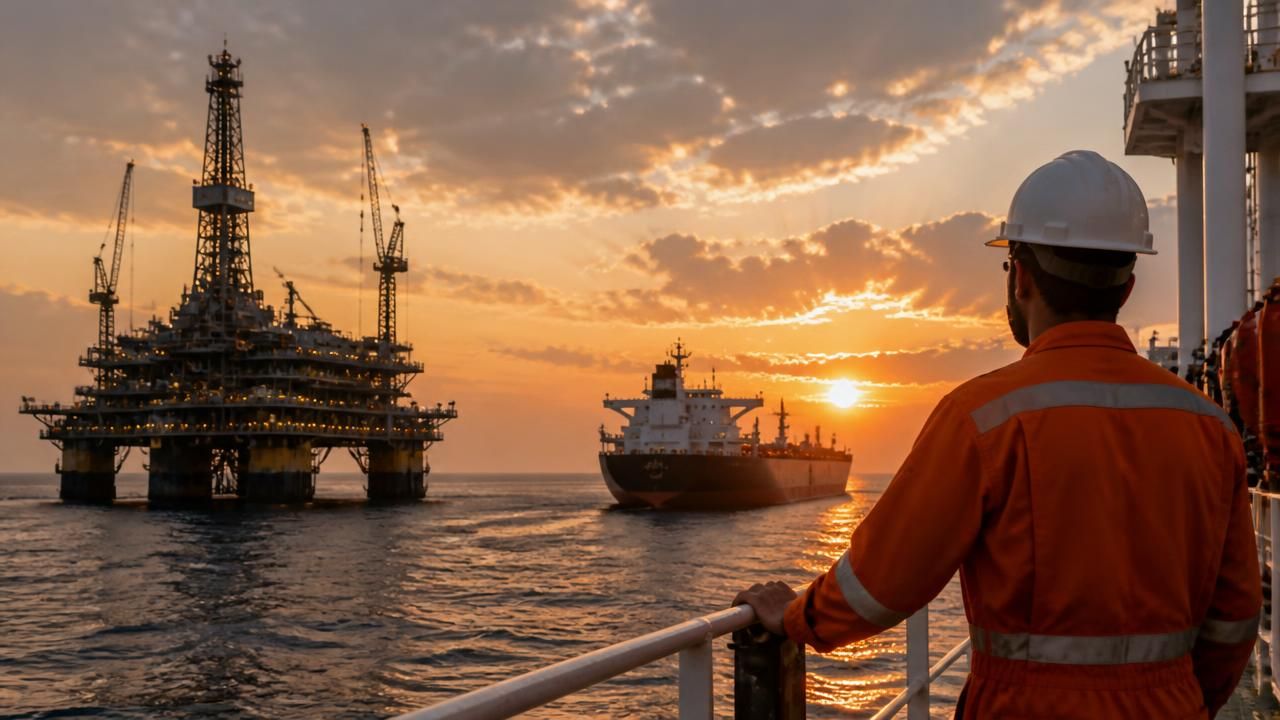
Middle East oil is flowing again almost exactly as it did before the war with Iran. So why is a barrel of benchmark crude still trading above US$100 — roughly 40% higher than it was before the conflict erupted? That question sits at the heart of a story being told differently across financial wires, aggregators and broadcast newsrooms this week, and the answers say as much about market psychology and the structure of global supply as they do about the war itself.
Bloomberg Markets frames the puzzle bluntly: the barrels are back, but the price is not coming down. Its explainer sets out five reasons crude has refused to retreat to pre-conflict levels. CNN en Español approaches the same facts from the opposite direction, asking how and why oil spiked to US$100 in the first place. A third thread, carried by MSN, shifts the lens from the commodity to the equity — arguing that Spain's Repsol has reasons to climb another 20% that go well beyond its Middle East exposure.
The five forces keeping crude near triple digits
According to Bloomberg's analysis, the persistence of triple-digit crude is not a single story but a stack of them:
- A risk premium that will not decay. Production has normalised, but the insurance markets, shipping lanes and trading desks that price geopolitical hazard have not. Every barrel moving through the region now carries a war-risk surcharge that did not exist before the conflict.
- Thin spare capacity. The world's shock absorber — the cushion of idle production that can be switched on within weeks — remains concentrated in a handful of producers. When the buffer is narrow, even small disruptions are priced as if they were large ones.
- Depleted inventories. Drawdowns during the disruption left commercial and strategic stockpiles lower than normal, and refilling them takes months of steady supply. Restocking demand is itself a source of upward pressure.
- Refining and logistics bottlenecks. Crude may be plentiful; the products the world actually consumes are not always where they are needed. Tight diesel and jet-fuel markets have repeatedly pulled crude benchmarks higher.
- Resilient demand. Neither higher prices nor a softer macroeconomic backdrop have meaningfully eroded consumption, particularly in emerging economies. Demand that fails to respond gives producers little incentive to discount.
Middle East oil is flowing almost as before the war — yet crude is still trading roughly 40% above pre-conflict levels.
Bloomberg Markets
How the spike happened
CNN en Español's coverage centres on the initial rupture: the moment oil punched through US$100 a barrel. For readers arriving late to the story, that framing matters. The run-up was not a slow grind but a sudden repricing, driven by fears of lost supply rather than actual lost barrels — a distinction that explains why prices have not fully unwound now that shipments have resumed. Markets priced the worst case first and have been reluctant to unpick it since.
The divergence in emphasis is telling. Bloomberg, writing for an investor audience, treats US$100 as a level to be explained and sustained. CNN, writing for a general audience, treats it as an event to be narrated. MSN's aggregation role is to surface both — and, in the case of its Repsol piece, to redirect attention toward who profits.
Beyond the barrel: the Repsol thesis
The most forward-looking of the four items is not about crude at all. MSN's report on Repsol argues the Spanish integrated energy group could gain another 20% on the Madrid bourse, and that the case rests on more than a high oil price. The reported drivers include:
- Upstream leverage with geographic spread. Repsol's production is not concentrated in the Gulf, which lets it capture elevated prices without carrying the same headline geopolitical risk as pure Middle East plays.
- Refining margins. A tight products market — one of Bloomberg's five reasons — flows directly into downstream earnings.
- Shareholder returns. Dividends and buybacks give the stock a floor that a pure price-taker lacks.
- A valuation discount to peers and an underappreciated low-carbon and renewables portfolio that analysts say is not fully reflected in the multiple.
In other words, the same five forces keeping oil near US$100 are, for an integrated European major, not purely a headwind. They are a margin story.
What to watch
Three things will determine whether US$100 becomes a ceiling or a floor. First, whether OPEC+ and its allies are willing to release spare capacity into the market — and whether they can, given how thin that cushion has become. Second, whether inventories rebuild fast enough to remove the restocking bid. And third, whether demand finally cracks under the weight of higher energy costs, which would do more to cool prices than any supply announcement.
For now, the consensus across all three outlets is uncomfortable but consistent: the physical disruption is over, and the financial one is not. Oil markets are pricing a war that has stopped shooting.