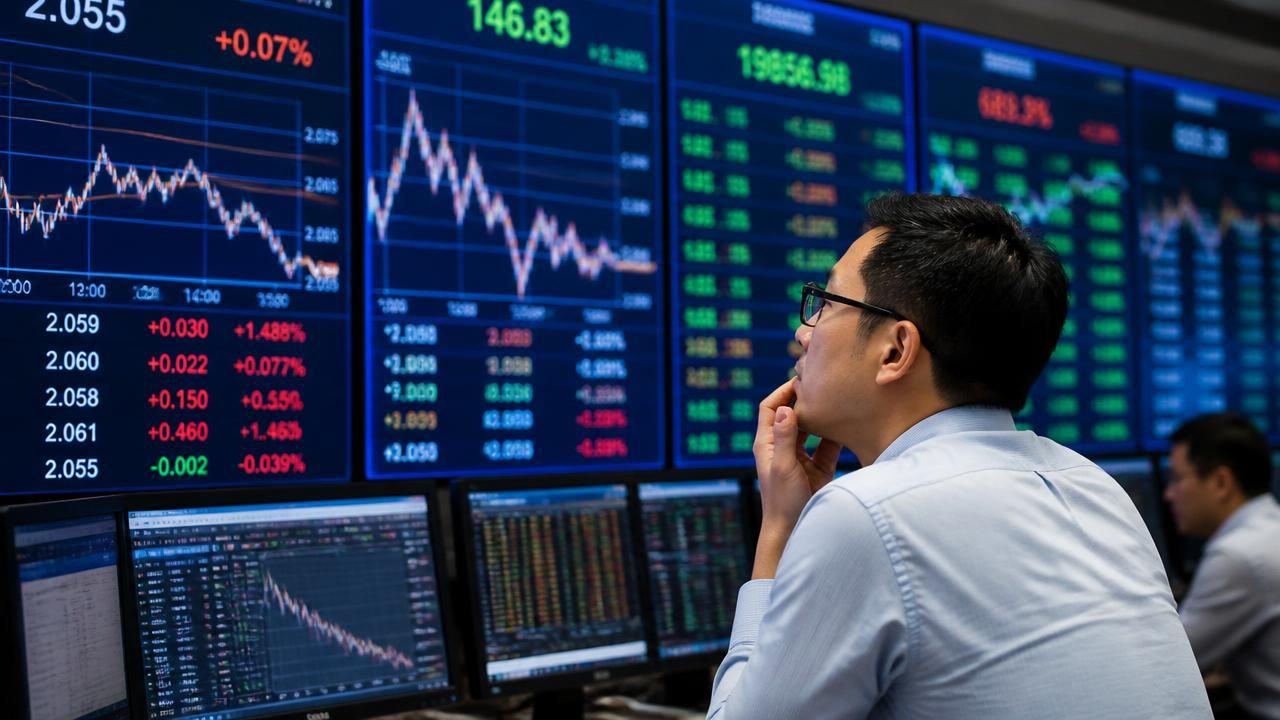
Asian markets spent the week absorbing the aftershocks of the Federal Reserve's first interest-rate increase since 2023, a move that rippled through sovereign debt, currency desks and equity trading floors from Tokyo to Seoul. Shorter-dated Asian sovereign bonds fell sharply, tracking declines in U.S. Treasuries, after the Fed not only raised rates but explicitly signaled that further tightening may be needed to bring inflation back to target. The dollar posted its biggest single-session gain since June, a move that reshaped positioning across the region's foreign-exchange markets.
The decision itself was widely anticipated; the guidance attached to it was not. That distinction explains many of the contradictory headlines that emerged from the region over the following days. Before the meeting, Asian equities had made only shaky gains as traders trimmed risk, oil slipped on demand concerns and the yen hovered near a seven-month high — a sign that some investors were already hedging against a policy shock.
Bonds Bear the Brunt
The most immediate transmission channel was fixed income. Shorter-dated Asian sovereign debt bore the brunt, with yields rising as investors recalibrated where the terminal rate might settle. The move extended beyond Asia's developed markets: the bond selloff spread quickly to emerging-market debt, where investors dumped duration on the view that a higher-for-longer U.S. rate path erodes the relative appeal of local-currency paper.
Japan was a notable exception to the broader regional pattern. Japanese government bonds rose, buoyed by gains in most U.S. Treasuries and by the yen's strength, which tends to support domestic demand for JGBs at the shorter end of the curve. The divergence underscores how the Fed's decision is filtering through each market differently, depending on local rate expectations, currency exposure and central-bank policy trajectories.
Shorter-dated Asian sovereign bonds fell, tracking moves in Treasuries after the Federal Reserve raised interest rates for the first time since 2023 and signaled further tightening to curb inflation. The dollar gained the most since June.
The Yen and the BOJ
Currency markets were the second pressure point. The dollar traded in a narrow range in the run-up to the Fed decision, with the yen near a seven-month high ahead of both the Fed and Bank of Japan meetings. That strength reflected a mix of safe-haven demand and expectations that Japanese policymakers may finally be preparing to step back from ultra-loose settings.
Solid U.S. economic data released alongside the Fed's decision nudged rate-hike expectations higher and gave the dollar fresh support, a dynamic that CNBC's market coverage highlighted as the primary driver of greenback sentiment. For Asian exporters, the combination of a firmer dollar and higher U.S. yields raises borrowing costs in dollar-denominated debt and squeezes local-currency returns for foreign investors.
Oil, Geopolitics and the Inflation Calculus
Layered on top of the monetary story is a fresh geopolitical shock. Renewed U.S.-Iran military strikes pushed oil toward $95 a barrel, with bond yields surging as traders priced in both higher inflation and the prospect of more aggressive Fed tightening. The energy spike cuts directly against the Fed's inflation-fighting rationale: a sustained move above $95 complicates the disinflation narrative that underpins any eventual pause.
The result has been a volatile global risk backdrop, with U.S. and European stock markets falling as the twin shocks of hawkish central banking and Middle East escalation hit sentiment simultaneously.
Equities: A Story of Two Halves
Equity markets captured the confusion most vividly. Global stocks fell immediately after the Fed delivered what traders characterized as a hawkish rate hike. Yet by the following session, Asian equities were rising again as rate-hike bets eased, with South Korea's Kospi jumping 1.44% and the yen extending its rally.
That rebound illustrates how differently the same information is being read. Bloomberg's coverage centered on the mechanical spillover from Treasuries into Asian and emerging-market credit. CNBC focused on U.S. data feeding dollar strength and hike expectations. Aggregated market wraps from MSN tracked the day-to-day oscillation — shaky gains before the decision, dollar steadiness, oil slips. CNBC-TV18, meanwhile, framed the aftermath as a relief trade, emphasizing regional equity gains and yen strength.
What to Watch
- Fed guidance: Any shift in language on the pace of further tightening will drive Asian FX, particularly the yen and the Korean won.
- Bank of Japan: A yen near seven-month highs sharpens the dilemma for policymakers weighing normalization against export competitiveness.
- Oil above $90: A sustained move toward $95 or higher reopens the inflation question the Fed is trying to close.
- Emerging-market debt: Watch for continued duration selling if U.S. yields push higher.
- U.S. data: Inflation prints and labor-market readings remain the single biggest swing factor for hike expectations.
The throughline across the week's coverage is a market caught between two forces: a Fed determined to demonstrate resolve on inflation, and an economic and geopolitical environment that keeps generating new sources of price pressure. For Asian investors, that means the dollar, the yen and the U.S. 10-year yield will remain the three dials that set the tone for everything else.